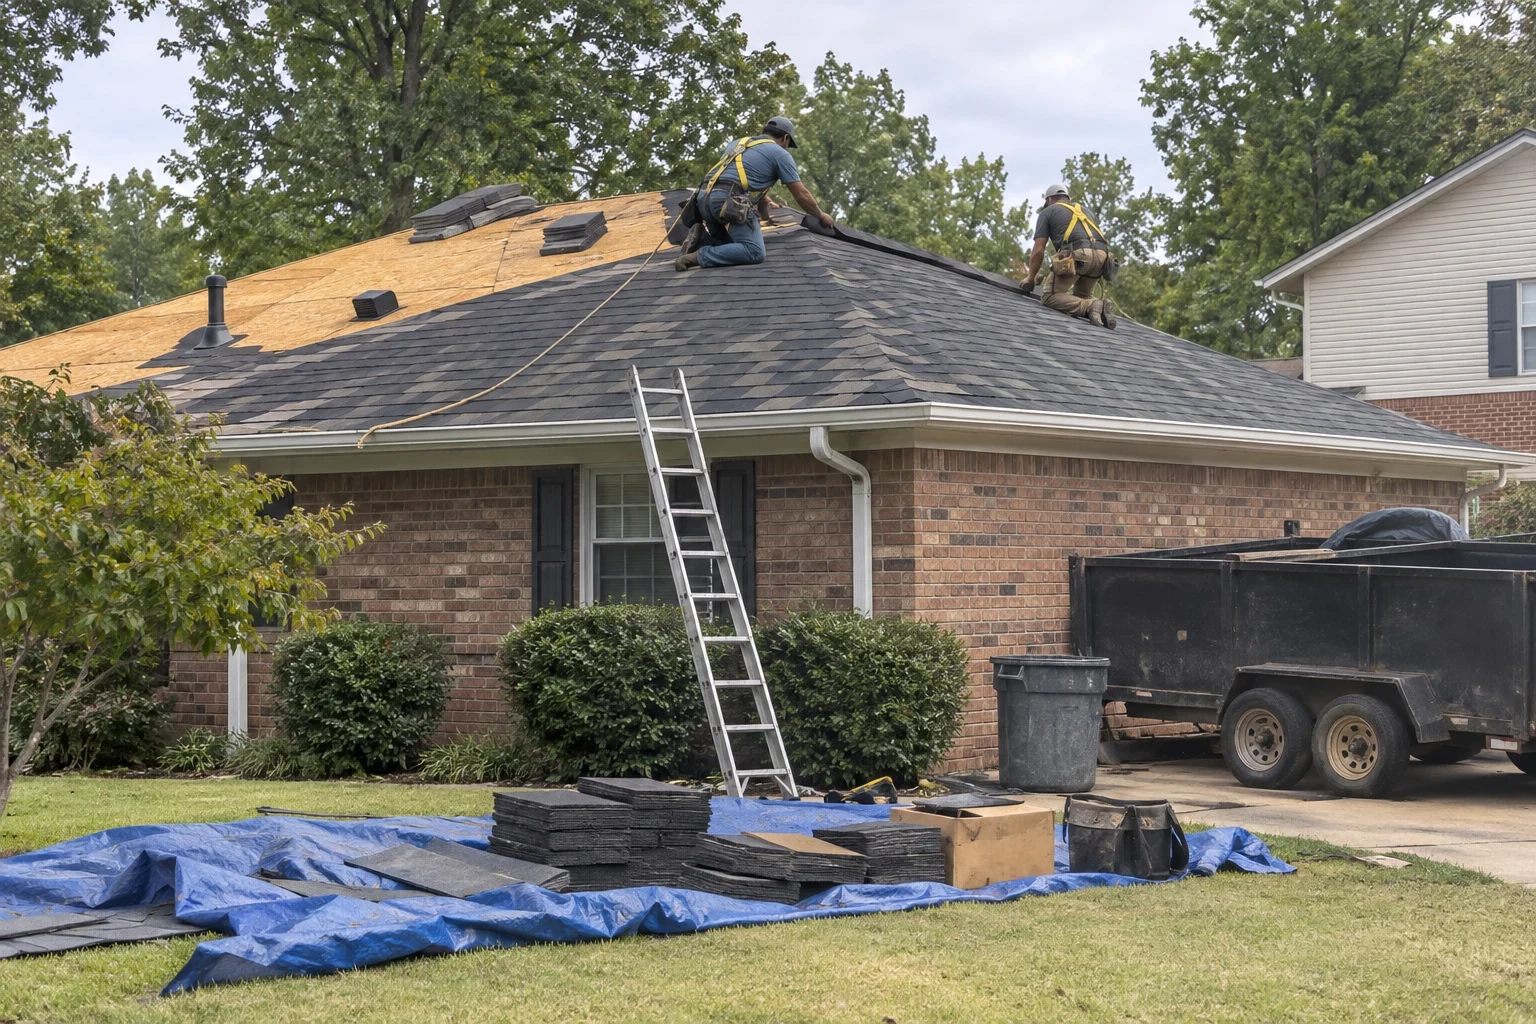
Anderson Creek Roofing That Begins With Photos of Every Finding
Shingle roof repair and full replacement, storm damage repair, gutters and siding make up our daily work across Anderson Creek, Spout Springs and Lillington. The first visit is a free inspection. You get photos of each finding, from creased shingle tabs to cracked pipe boots, before anyone talks about price.
- Free roof inspection
- Photo report of findings
- Adjuster meeting help
- Financing through Acorn Finance
Roofing Services for Your Home
Most calls start with a question about one spot: a water stain on a bedroom ceiling, shingles in the yard after a storm, or a gutter pulling away from the fascia. We trace that symptom back to the part that failed, then tell you whether roof repair will hold or roof replacement makes more sense. We also handle storm damage repair, roof inspections, gutters, siding and commercial roofing. Open any service page to read about the usual failure points, our repair method and the cost drivers for that specific work.
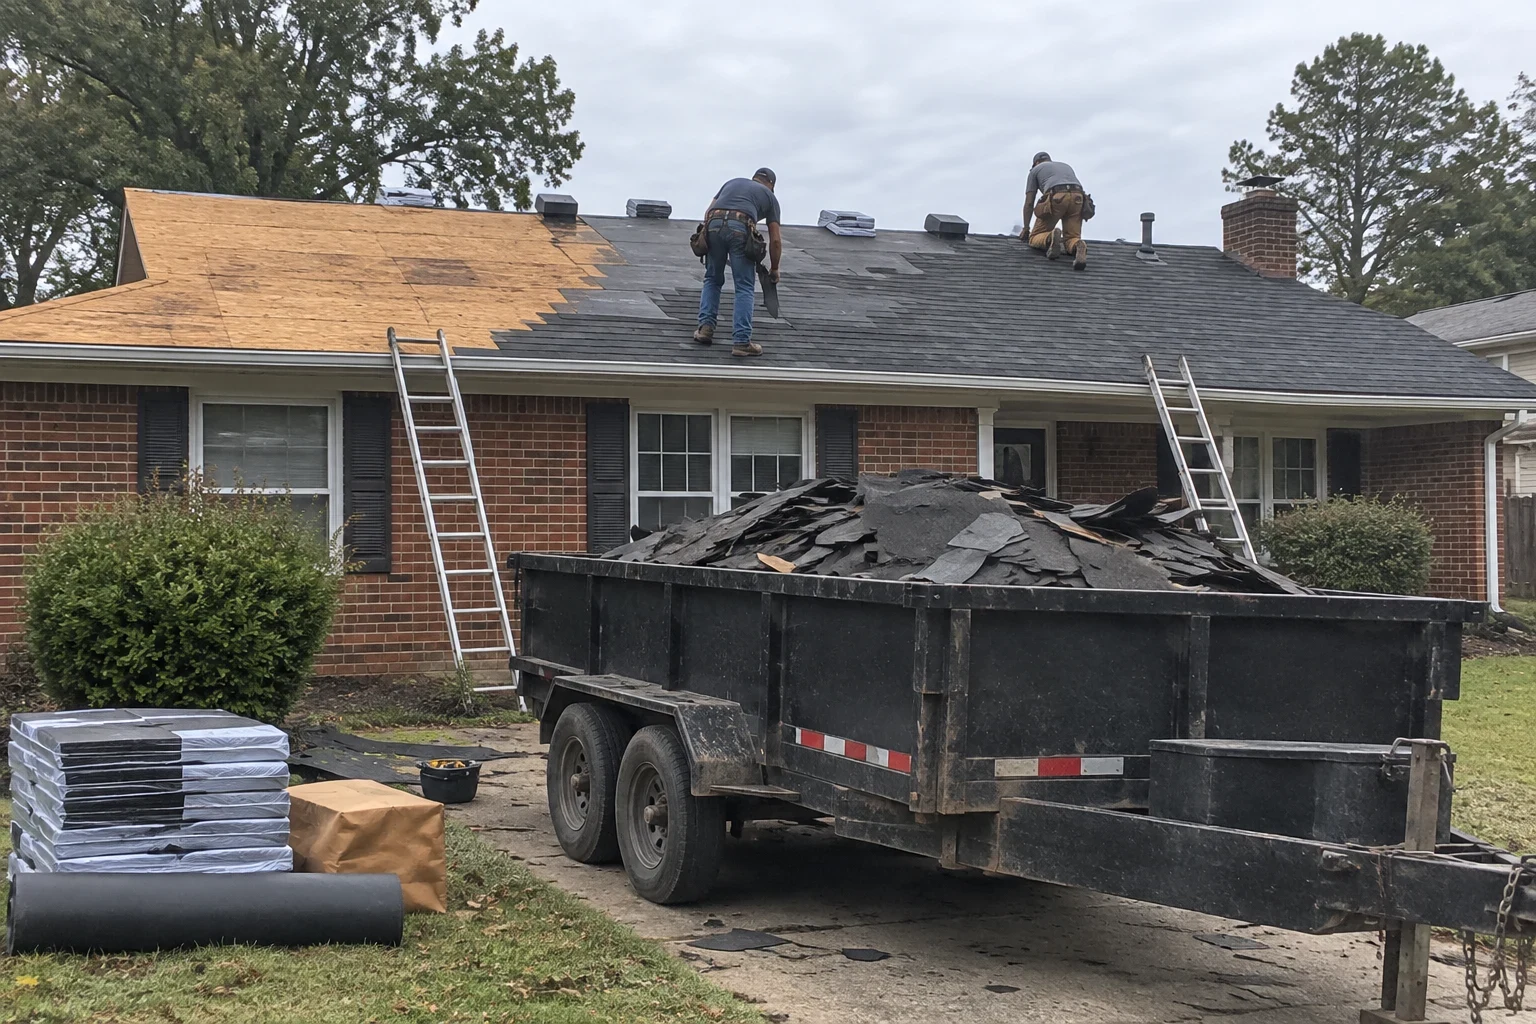
Roof Replacement
Full tear-off and new roof system, from decking and underlayment to ridge vents, with photos of every problem we find and help with your insurance claim.
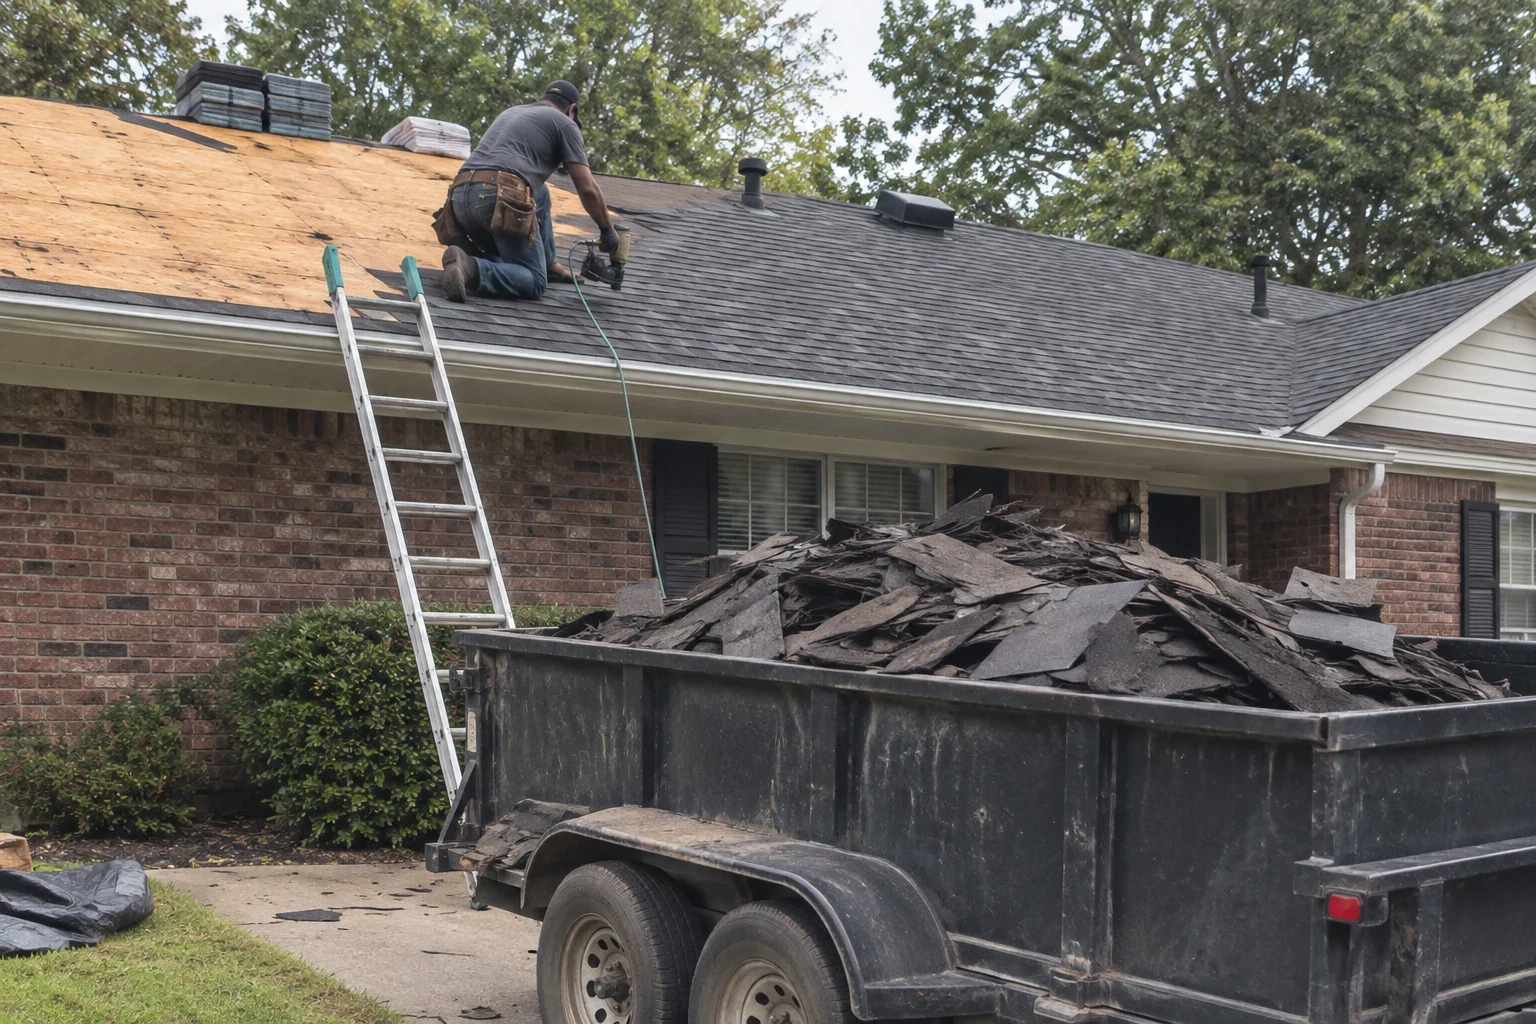
Roof Repair
Leak tracing and targeted repairs for pipe boots, flashing, shingles and decking, with photos of what failed and why.
Roof Inspections
A free top-to-attic roof check with dated photos of every issue we find, useful for planning repairs or backing up an insurance claim.
Storm Damage Repair
After hail or high wind, we inspect your roof, photograph each damaged component and repair it, with help through the insurance claim if you file one.
Gutters
New gutters and downspouts sized to your roof area, hung on hidden hangers, and pitched so rainwater leaves your home's foundation instead of pooling against it.
Commercial Roofing
Repair, drainage fixes and replacement for TPO, EPDM, modified bitumen and metal roofs on existing commercial buildings, with every finding documented in photos.
Siding
Vinyl and fiber cement siding repair and replacement, with the damage photographed and explained before you decide anything.
What Changes a Roofing Estimate
Square footage alone does not set the price of a roof. The shape of the roof, the condition of the wood under the shingles and the materials you pick carry most of the weight. Below are the items that shift an estimate the most.
Your estimate comes after a free inspection and lists each line item, so you can match the price to the photos. If your insurer approves the work, we walk through how our estimate lines up with the adjuster's scope.
- Roof size and pitch
- Roofers price by the square, which is 100 square feet of roof surface. A steep pitch takes longer to work safely and uses more material per square of floor space below it.
- Condition of the decking
- Soft or delaminated plywood and OSB must come out before the new roof is installed. Rot often stays hidden until tear-off, so your estimate states how each replacement sheet is priced if we find it.
- Layers to remove
- A second layer of shingles adds tear-off labor and disposal weight. It also hides the deck, which makes a clean tear-off the only way to inspect it properly.
- Flashing, vents and penetrations
- Chimneys, skylights, sidewalls and plumbing vents each need their own flashing or boot. More penetrations mean more detail work, and more places where a shortcut would leak later.
- Ventilation and attic airflow
- Ridge vents and soffit intake work as a pair. If the attic runs hot and humid through a long summer, correcting the airflow adds cost now and protects the new shingles from premature aging.
- Shingle choice
- Architectural shingles cost more than three-tab but carry higher wind ratings and a longer service life. We price both when it makes sense so you can compare.
About Roofing Anderson Creek
We are a local roofing company working on homes in and around Anderson Creek. Most of our work is shingle repair and replacement, storm damage, and the gutters and siding that keep water moving off and away from your home.
We built the business around one habit: show the homeowner what we see. A photo of a cracked boot around a plumbing vent explains a ceiling stain better than any sales pitch, and the same photos help an adjuster understand your roof. When a repair is the right call, we say so and price the repair.
You can read more about how we operate on our About page, or check whether we cover your town on the Service Areas page.
- License
- NC and SC unlimited builder license
- In business
- In business 10 years
- Warranty
- 5-year workmanship warranty on architectural shingle roofs
How a Roof Job Runs
This is the order of things from the first phone conversation to the final walk-around, so the work day holds no surprises.
- 1
Your call and our inspection
Tell us what caught your eye, like a ceiling stain, a lost tab or a sagging gutter, and we set a visit for a day that works for you. On the roof we look over shingles, flashing, vents and gutters, and when we can get into the attic, we check the decking from below as well.
- 2
Photos and your options
Every finding gets its own photo and a short note on what caused it. If the damage looks like it came from a storm, we explain how filing a claim works and what your adjuster is likely to check.
- 3
Claim support or a straight estimate
When you file, we can meet the adjuster and line up the scopes once both are available. When you pay directly or use financing, you get a written estimate itemized line by line.
- 4
Work day
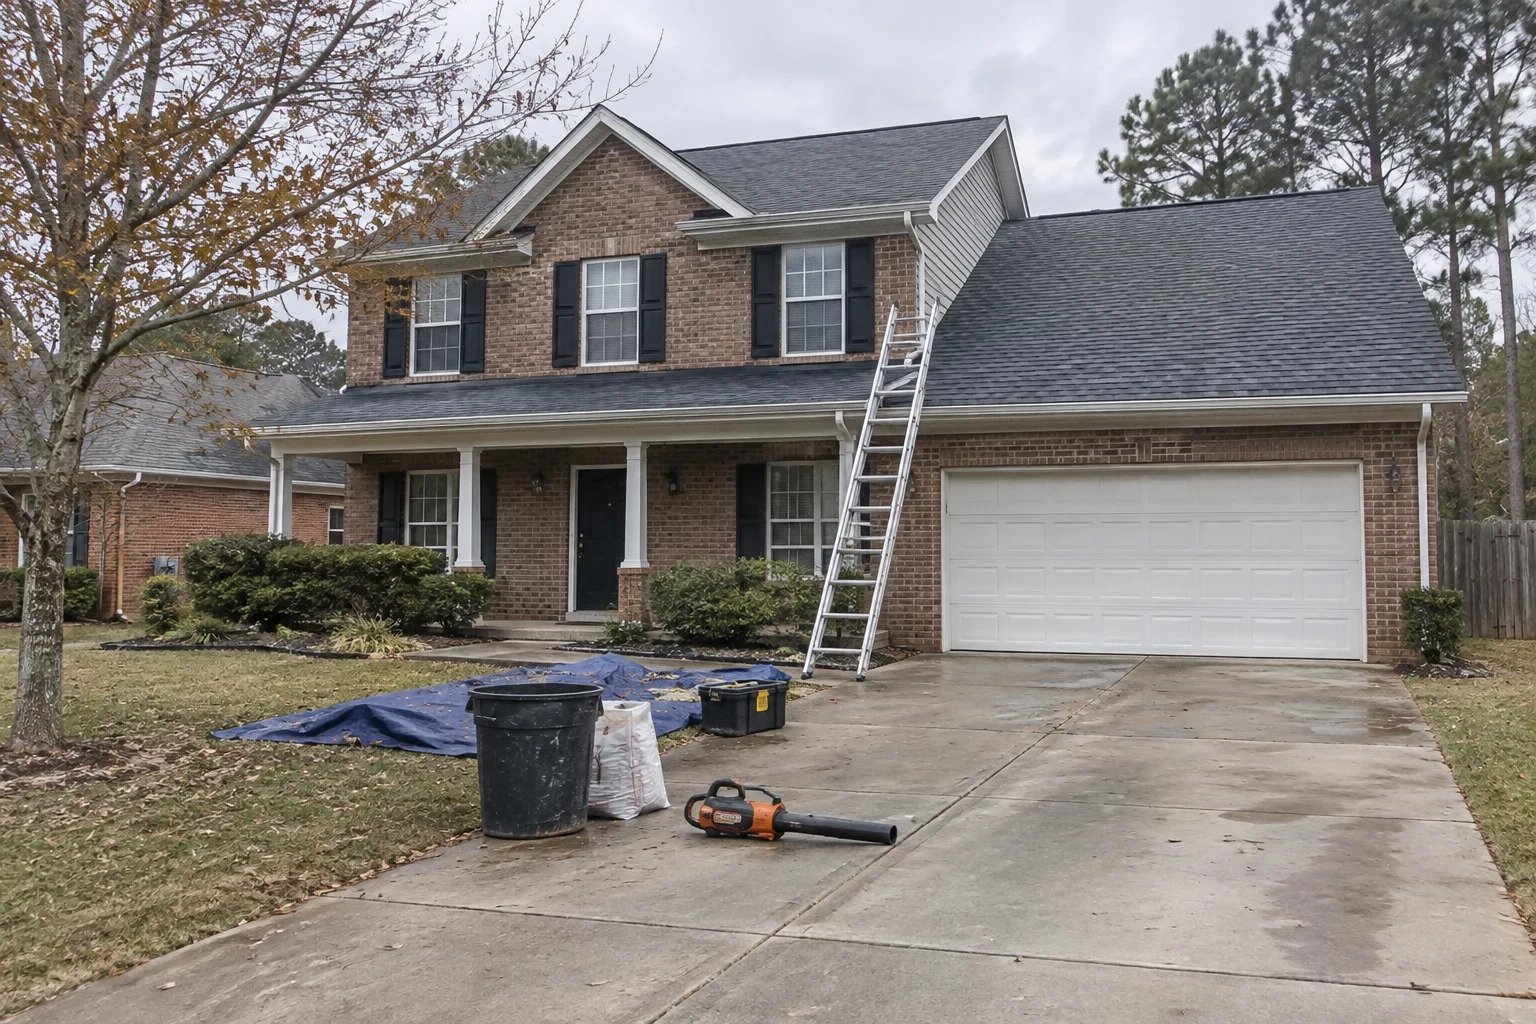
Before tear-off, we cover your shrubs and protect the driveway. Underlayment, drip edge, flashing and shingles are installed in the correct order, and we call you right away if the decking needs attention.
- 5
Cleanup and final walk-around
We sweep the lawn and driveway with magnets for loose nails, haul every bit of debris away and check the finished roof with you.
How We Work on Your Roof
Our focus is helping you document damage and understand the insurance claim process, without promising what only your insurer can decide. That shapes everything from how we photograph a roof to how we write an estimate.
Photos before opinions
We photograph every finding with enough context to locate it: the slope, the nearest vent or valley, and a close-up of the damage itself. You get the report whether or not you hire us.
Straight talk on what insurance decides
Your adjuster and your policy decide coverage, not us. We explain the difference between wind and hail damage, which most policies cover, and age-related wear, which they usually don't, so you can file with realistic expectations.
We meet your adjuster on the roof
When the adjuster visits, we can be there to point out what we documented, from bruised granules to lifted shingle seals. We answer questions about materials and measurements. The coverage call stays with your insurer.
An honest repair-or-replace answer
A roof with a few blown-off tabs and sound decking usually calls for a repair. Brittle shingles and granule loss on every slope point the other way. We say which situation applies to your roof and point to the photos that back it up.
Financing when the timing is tight
Financing is available through Acorn Finance for homeowners who would rather spread out the cost of a repair or replacement.
Where We Work
Our crews start out from Anderson Creek and cover homes across the surrounding part of North Carolina. To the north and east, that means Spout Springs, Barbecue, Lillington, Buies Creek and Erwin. To the south, it means Spring Lake, Fayetteville and Eastover. Summer thunderstorms and the leftovers of tropical systems reach every one of these towns, so the storm damage, roof repair and gutter calls we answer look much alike wherever your home sits.
- Anderson Creek
- Spout Springs
- Barbecue
- Spring Lake
- Fayetteville
- Lillington
- Erwin
- Eastover
- Buies Creek
For homes a bit beyond these towns, mention your location on the phone and you'll get a straight yes or no on whether we travel there.
Questions Homeowners Ask Us
Something not covered here? (910) 858-8300
Will my insurance pay for a new roof?
That comes down to your policy and the cause of the damage. A sudden wind or hail event is often covered; wear from age, weak ventilation or a poor original install usually is not. We document our findings and tell you which way it probably leans, but the adjuster decides coverage.
Should I call you or my insurance company first?
Plenty of homeowners start with our free inspection to learn whether the damage justifies a claim. If the photos show ordinary wear, filing may not be worth it. If they show storm damage, you open the claim with evidence ready.
Will you meet my adjuster at the house?
Yes. We can be on site for the adjuster's visit and help you through the claim, showing the damage in our photos and answering questions on materials and measurements. We are not your adjuster and we do not negotiate your policy.
How do you choose between a repair and a new roof?
Three things guide us: how widely the damage spreads, how brittle the shingles are and whether the decking below is sound. A failed vent boot or a few missing tabs can be repaired. When every slope has lost its granules, the edges curl and the deck gives underfoot, a new roof is usually the smarter spend. Either way, the photo report backs up our answer.
Does the roof come with a warranty?
You can get a GAF Golden Pledge manufacturer warranty. When we review your estimate, we explain what it covers and which roof systems qualify.
Can I finance the work?
Yes. Financing through Acorn Finance works for repairs and replacements. Mention it when you call, and after the inspection we'll show how it applies to your itemized estimate.
Do I need to be there for the inspection?
Not for the roof work, though a few minutes together before or after helps. If we can get into the attic, we check the underside of the decking for stains and soft areas, which often reveals more than the shingles.
Find Out What Your Roof Looks Like Up Close
Our free inspection shows your roof's actual condition in photos, with each finding explained in plain terms. Then you choose: repair, replace or file a claim with your insurer.